

Dollarbird Pro
Dollarbird Apps SRL
- 3.3
- 128.00 Reviews
- 50.00K
- Downloads
- Free
- Price
Screenshots
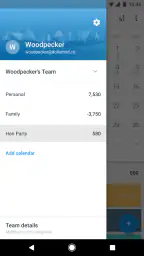
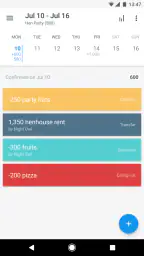
Dollarbird Pro Pros and Cons
Pros
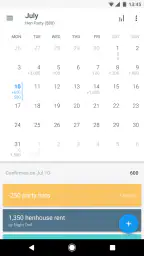
- Calendar-based design makes future cash flow easy to visualize.
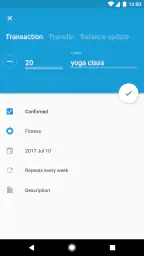
- Supports recurring transactions for rent, bills, and regular income.
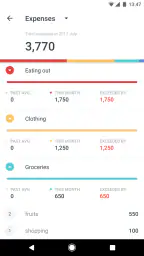
- Custom categories help organize spending around personal priorities.
- Useful for planning shared finances with partners or family members.
- Works well for users who prefer manual control over automatic bank syncing.
Cons
- Manual transaction entry can become tedious with frequent daily spending.
- No automatic bank connection means balances may need regular updating.
- Collaboration features may require extra setup for all participants.
- Advanced budgeting tools are less extensive than those in dedicated finance apps.
- A missed entry can quickly make projected balances inaccurate.
 Analysis by All-app
I approached Dollarbird Pro as a practical money diary rather than a full banking replacement. It is a finance app from Dollarbird Apps SRL that puts spending, income, and expected bills into a calendar-style view, with an added AI angle in its store summary. That basic idea matters because many budgeting tools make you think in categories first, while this one encourages you to think in dates: what happened, what is due soon, and whether the next few weeks look manageable.
After using it, my impression is mixed but fairly clear. The calendar format can make personal finances easier to understand, especially if your main problem is forgetting irregular payments or losing track of cash flow between paydays. At the same time, it asks you to keep your records tidy. If you want automatic bank synchronization, a highly detailed investment dashboard, or a budgeting system that does nearly everything without manual attention, this is probably not the best match.
How the calendar approach changes everyday budgeting
The most useful change is visual. Instead of opening a conventional expense list and seeing isolated transactions, I can place a payment on the day it affects my life. Rent, subscriptions, groceries, transport, freelance income, and one-off purchases become part of a timeline. That makes the app particularly suitable for people who ask, “Will I have enough available when this bill arrives?” rather than only, “How much did I spend this month?”
That distinction is easy to underestimate. A category budget may tell me that dining out is getting expensive, but a calendar can show why the middle of the month feels tight: several recurring commitments may land close together, while income arrives later. For someone paid monthly, paid irregularly, or managing a household with different payment dates, this perspective is more immediately useful than a simple pie chart.
I also found the format helpful for separating known future commitments from guesses. A confirmed bill can be entered on its expected date, while a flexible cost such as food can be estimated across several days. That creates a more realistic picture than treating every expense as if it happened at the same time. The trade-off is that the picture is only as good as the entries. This is not a magic financial forecast; it is a planning surface that rewards consistent updates.
A realistic example would be a user who receives a salary near the start of the month, pays housing costs shortly afterward, and has several annual renewals scattered through the year. In a normal notes app, those renewals are easy to overlook until the money leaves the account. In Dollarbird Pro, I would record them ahead of time and check the calendar before making a large discretionary purchase. The value is not in predicting the future perfectly. It is in making future pressure visible early enough to act.
What the AI angle adds to the experience
The app presents itself as a personal finance calendar with a spark of AI, but I would not choose it solely because of that phrase. The strongest reason to use it is still the calendar workflow. Any intelligent assistance is most useful when it reduces the effort of recording or interpreting information, not when it distracts from the basic habit of checking what is coming next.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
That is also where I would keep expectations sensible. An AI-assisted finance feature should be treated as a convenience, not as an authority on financial decisions. I would still review dates, amounts, and categories before relying on a forecast. A mistaken recurring payment or an incorrectly understood transaction could make a clean-looking calendar misleading. The app is best used as a planning aid while the user remains responsible for checking the underlying entries.
For a beginner, that may sound cautious, but it is actually reassuring. The app does not need to replace judgment. Its job is to help organize the information that I already know about my finances and make patterns easier to notice. If the intelligent elements save time without hiding the original details, they can be useful. If a user prefers to understand every entry manually, the calendar itself remains the more important part of the experience.
Who will benefit most from the layout
I would recommend it first to people with predictable commitments but imperfect visibility. That includes students managing rent and recurring services, families coordinating shared household expenses, freelancers who need to compare uneven income with fixed bills, and anyone who repeatedly says, “I knew that payment was coming, but I forgot when.” The timeline gives those users a concrete place to plan.
It can also suit someone who dislikes traditional budgeting language. Not everyone naturally thinks in envelopes, categories, or percentages. Some people understand money better as a sequence of events. For them, placing a payment on a date may feel more intuitive than deciding whether it belongs in a strict monthly allocation.
On the other hand, I would hesitate to recommend it to a user who wants a completely automatic system. Manual financial tools require a routine, and even a well-designed calendar will become unreliable if income and expenses are not updated. People with complicated portfolios, business accounting needs, or strong requirements for bank-level automation may be better served by a specialized service built for those tasks.
Trust, controls, and the moments that deserve care
Because this is a finance app, trust matters more than visual polish. I would judge it less by whether the calendar looks attractive and more by whether I can understand what is being recorded, what I am choosing to share, and how much control I retain over my account. The developer is Dollarbird Apps SRL, and the app has been available since late July of 2017, which gives it a longer presence than a newly launched budgeting experiment. Its current version is 6.1.8, and it supports Android devices running version 5.0 or later.
Its public store profile shows an average rating of 3.3 from 591 ratings, alongside 128 written reviews and more than 50K installs. I read those figures as a reason to investigate the fit carefully rather than as a simple verdict. The audience is established, but the rating also suggests that the experience may not satisfy everyone. In finance software, a lower-than-excellent score can reflect friction around synchronization, account expectations, usability, or subscription boundaries, so I would pay attention to how the app matches my preferred workflow before committing to it.
The app is free to install and is marked for Everyone, with in-app purchases ranging from $7.99 to $79.99 per item. That makes the first step relatively low-risk: I can explore the basic experience before deciding whether any paid option is worthwhile. Still, I would look closely at the purchase screen and the wording around upgrades. A free download is not the same as an entirely free planning system, and a finance tool should make the difference between accessible functions and paid functions easy to understand.
What I would verify before entering sensitive information
My first trust check would be the permission and privacy screens visible on the device and in the store listing. I would not assume that a calendar-based money planner needs broad access to unrelated phone content. If the app asks for a permission, I would read why it is requested and decide whether that permission is necessary for the feature I want. A cautious user can begin with the smallest amount of information needed to test the workflow.
I would also distinguish between entering a budget manually and connecting a financial account. Those are very different trust decisions. Manual entries may be enough for a user who wants planning without importing transaction history. A connected account, if offered in the version being used, would deserve a separate review of the provider, authorization screen, revocation process, and data handling terms. I would never treat an AI label as a reason to share more information than the task requires.
The most sensitive moments are predictable. They include creating an account, importing transactions, allowing access to contacts or notifications, accepting a trial or paid upgrade, and deleting data. At each point, I would pause and ask what the app is requesting, whether I can decline it, and what I lose by declining. That habit is more useful than trusting a general privacy impression based on the interface.
Another practical check is whether the app clearly distinguishes planned entries from completed ones. A forecast that looks like a confirmed balance can create false confidence. Before making a financial decision, I would inspect the date, amount, status, and source of each important entry. If the app offers AI-generated organization or suggestions, I would treat those as prompts to review, not as verified banking records.
Keeping control of the account and the routine
User agency is strongest when I can correct an entry quickly. Calendar planning depends on small details: moving a bill by a day, changing a recurring amount, marking an expected payment as completed, or removing an outdated commitment. I would test those actions during the first session rather than waiting until the calendar becomes crowded. If corrections are cumbersome, the entire method becomes harder to maintain.
I would also create a simple personal rule for data entry. For example, I might record fixed commitments as soon as I know their dates, then review flexible spending at the end of each day or week. This avoids the common mistake of trying to reconstruct an entire month from memory. The app becomes more dependable when I use it as an ongoing diary instead of a rescue tool after overspending has already happened.
One less obvious advantage of a calendar is that it can support “what if” thinking without requiring a complicated spreadsheet. I can consider the effect of a large purchase by placing it on the intended date and looking at the surrounding commitments. I can compare an annual payment with a monthly alternative by entering each pattern separately. The insight comes from timing, not just from the total amount. That is especially useful when a purchase is affordable in isolation but awkward alongside several nearby obligations.
There is a corresponding limitation: estimates can create a false sense of precision. A projected grocery amount is not the same as money already reserved, and an expected freelance payment is not guaranteed income. I would label my own entries mentally as confirmed, likely, or uncertain, even if the interface uses different terminology. The more uncertain the input, the more conservative my decision should be.
How it compares with familiar alternatives
Compared with a spreadsheet, Dollarbird Pro is more approachable for date-based planning. A spreadsheet can be more flexible, but it requires building formulas, formatting, and views before it becomes comfortable. The calendar gives me a ready-made way to see timing. A spreadsheet remains better for users who want custom calculations, detailed reporting, or complete control over the structure.
Compared with a notes app, this is a more purposeful environment. Notes are quick for recording a payment, but they rarely show the relationship between several future commitments. Dollarbird Pro earns its place when the user wants to revisit the information and reason about cash flow rather than simply store a reminder.
Compared with bank apps, the emphasis is different. A bank app is usually the authoritative place to inspect actual balances and transactions. A planning calendar is better for adding expected events, considering upcoming pressure, and organizing information across accounts or payment methods. I would use the two for different jobs rather than expecting one to replace the other.
Compared with envelope-style budgeting tools, this app may feel less demanding for someone who does not want to allocate every unit of income in advance. The calendar approach is more about timing and awareness. The downside is that it may provide less discipline for a user whose main challenge is category overspending. If dining, shopping, or entertainment limits are the central issue, a category-first system could be more effective.
Small habits that make the app more dependable
I would start with only the commitments that genuinely affect decisions: income dates, housing, utilities, debt payments, subscriptions, insurance, and known annual costs. Adding every minor purchase immediately can make the calendar noisy and discourage regular use. Once the main structure is useful, I would add flexible spending in a way that matches my routine.
I would review the next few weeks before making a nonessential purchase, not merely check the current balance. That is the calendar’s strongest practical habit. I would also revisit recurring entries whenever an amount changes, because an old fixed value can quietly distort the future view. Finally, I would keep a separate record of anything legally or financially important until I am comfortable with how the app stores and exports information.
For shared finances, I would agree with the other person on what gets entered and who is responsible for updates. A shared calendar can be useful only if everyone interprets planned and completed items in the same way. If one person records expected expenses while another records only completed transactions, the timeline may look inconsistent. Establishing that convention is more important than filling the calendar with detail.
Where I land after using it
Dollarbird Pro is a focused choice for people who want to understand money through dates. I like the way it turns upcoming commitments into something visible and discussable, and I think that can be more motivating than a dense financial dashboard. The app is particularly convincing when the problem is cash-flow timing, forgotten renewals, or irregular income rather than a lack of category limits.
My caution is equally important: this is not a substitute for checking real account balances, reading payment terms, or reviewing privacy and permission choices. The AI element should support attention, not replace it. I would begin with modest information, test editing and account controls, and decide whether the paid features offer enough value before spending money inside the app.
In the end, I would recommend trying it to a friend who wants a calmer view of the month and is willing to maintain a financial calendar. I would steer someone else toward a bank-connected tracker, spreadsheet, or envelope budget if automation, advanced reporting, or strict category control matters more. The best reason to choose this app is not that it promises to manage everything; it is that it makes the timing of your financial life easier to see and question.
Frequently Asked Questions
What is Dollarbird Pro used for?
Dollarbird Pro is a personal finance and budgeting app designed to help you track income, expenses, bills, and upcoming financial commitments in one calendar-based view. Instead of only showing past transactions, it lets you see how your balance may change over time. This makes it useful for planning recurring payments, monitoring spending habits, and avoiding surprises before they affect your available money.
How does the calendar-based budgeting system work?
The app organizes financial activity by date, allowing you to add income and expenses to the days when they occur. You can create recurring transactions for items such as rent, subscriptions, salary, or utility bills, then review your projected balance across the calendar. It is particularly helpful for users who prefer a visual timeline, although accurate results depend on entering transactions consistently and correctly.
Does Dollarbird Pro connect to my bank accounts automatically?
Dollarbird Pro is primarily designed around manually entered financial information rather than relying entirely on automatic bank synchronization. This gives you more control over what is recorded and can be useful for privacy-conscious users, but it also means you must remember to add purchases, deposits, and adjustments yourself. Before downloading, check the current store listing because supported synchronization and account features may vary by version or region.
Is Dollarbird Pro suitable for managing finances with other people?
The app can be useful for households, couples, or small groups that want to monitor shared financial plans, depending on the collaboration features available in the current version. A shared calendar can make recurring bills and expected income easier to coordinate. However, users should review whether the plan includes synchronization across devices, multiple users, or shared access, since these options may depend on the subscription or platform.
Is Dollarbird Pro free, and are there any limitations?
Dollarbird Pro may require a purchase or subscription, while some versions or related editions may offer limited functionality before payment. Potential differences can include the number of calendars, advanced planning tools, synchronization, collaboration, or access to premium features. Pricing and included benefits can change, so it is important to read the Google Play or App Store description carefully and review renewal terms before confirming a purchase.


